
Cleveland-Cliffs Inc
XMUN:CVA


Decide at what price you'd be comfortable buying and we'll help you stay ready.
|
C
|
Cleveland-Cliffs Inc
XMUN:CVA
|
US |

|
Hanjaya Mandala Sampoerna Tbk PT
F:HSZ
|
ID |

|
Eenergy Group PLC
F:A1Z1
|
UK |

|
Luca Mining Corp
F:Z68
|
CA |

|
Banco de Sabadell SA
MAD:SAB
|
ES |
|
R
|
Rockwell Automation Inc
F:RWL
|
US |
|
D
|
Diageo PLC
SWB:GUI
|
UK |

|
Synnex Technology International Corp
TWSE:2347
|
TW |
|
G
|
Gilead Sciences, Inc
F:GIS
|
US |
|
S
|
Shanghai Zhonggu Logistics Co Ltd
SSE:603565
|
CN |
|
TFS Financial Corp
NASDAQ:TFSL
|
US |
|
Fineos Corporation Holdings PLC
ASX:FCL
|
IE |
|
M
|
MSC Industrial Direct Co Inc
F:98M
|
US |
|
Haier Smart Home Co Ltd
SSE:600690
|
CN |

|
Orell Fuessli AG
F:OFH
|
CH |

|
Henkel AG & Co KGaA
XETRA:HEN3
|
DE |
|
U
|
Ulta Beauty Inc
SWB:34U
|
US |
|
M
|
Mattel Inc
DUS:MTT
|
US |

|
Independent Bank Corp (Massachusetts)
NASDAQ:INDB
|
US |
|
W
|
Westpac Banking Corp
F:WBC
|
AU |
Cleveland-Cliffs Inc
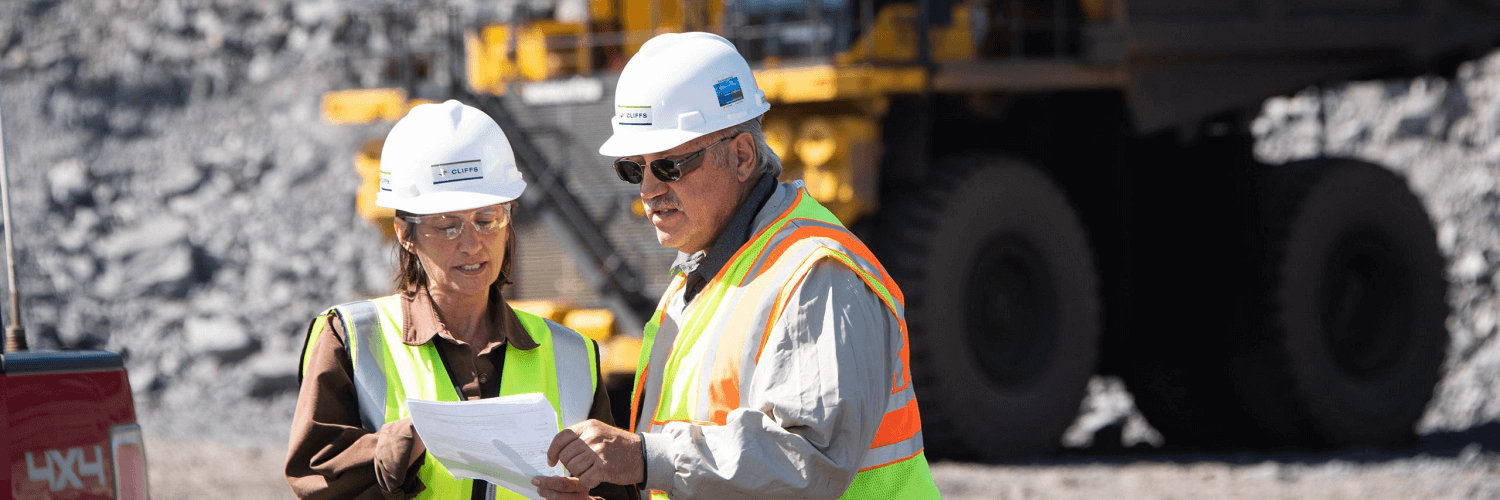
Cleveland-Cliffs makes iron ore pellets and steel products, with a strong focus on flat-rolled steel used by factories and makers of cars, appliances, machinery, and construction goods. It also owns iron ore mines and processing plants, so it can supply much of the raw material needed for its own steel mills. In simple terms, it sits in the middle of the industrial supply chain: it takes mined ore and turns it into steel that other companies use to build things. The company makes money by selling steel sheet, plate, stainless and electrical steel, plus iron ore pellets and related metal products. Its main customers are automakers, metal processors, manufacturers, and other industrial buyers that need large, steady shipments of steel. These customers usually sign contracts or buy through ongoing supply relationships rather than one-off retail sales. What makes Cleveland-Cliffs different is its vertical integration. Instead of buying most of its raw material from others, it controls mining, pelletizing, and steelmaking under one roof. That gives it tighter control over quality and supply, especially for demanding uses like automotive steel, where consistent specs and reliable delivery matter a lot.
Cleveland-Cliffs makes iron ore pellets and steel products, with a strong focus on flat-rolled steel used by factories and makers of cars, appliances, machinery, and construction goods. It also owns iron ore mines and processing plants, so it can supply much of the raw material needed for its own steel mills. In simple terms, it sits in the middle of the industrial supply chain: it takes mined ore and turns it into steel that other companies use to build things.
The company makes money by selling steel sheet, plate, stainless and electrical steel, plus iron ore pellets and related metal products. Its main customers are automakers, metal processors, manufacturers, and other industrial buyers that need large, steady shipments of steel. These customers usually sign contracts or buy through ongoing supply relationships rather than one-off retail sales.
What makes Cleveland-Cliffs different is its vertical integration. Instead of buying most of its raw material from others, it controls mining, pelletizing, and steelmaking under one roof. That gives it tighter control over quality and supply, especially for demanding uses like automotive steel, where consistent specs and reliable delivery matter a lot.
EBITDA rebound: Cleveland-Cliffs said Q2 adjusted EBITDA rose to $286 million, its best quarter in 2 years, and free cash flow turned positive after 2 years of negative cash flow.
Q3 outlook: Management guided to about $575 million of adjusted EBITDA in Q3, saying higher prices, lower costs and higher shipping volumes are all coming together at once.
Pricing tailwind: The company said average selling price rose by $76 per ton in Q2 and expects another $55 per ton increase in Q3 as contract pricing catches up to the stronger market.
Volumes improving: Shipments were just over 4 million tons in Q2, but the company expects more than 4.3 million tons in Q3 as maintenance disruptions fade and backlogs stay strong.
Auto strength: Management said automotive demand remains a major driver, highlighted by top supplier awards from Toyota and General Motors and the strongest auto shipments in 2 years.
Cash and debt: Management said debt paydown remains the top capital allocation priority, with leverage expected to fall below 2.5x by this time next year.
Policy support: The company credited U.S. trade enforcement and reshoring trends for better pricing and demand, while warning that Canadian protection measures remain insufficient for Stelco’s galvanizing business.